A practical framework for evaluating receivables-based working capital
For many growing companies, the central cash flow problem is not a lack of revenue. It is the delay between completing a sale and collecting the cash. A business may report rising sales, a healthy gross margin, and a full pipeline while still struggling to fund payroll, purchase materials, or accept its next large order. Accounts receivable finance addresses that timing problem by converting qualified commercial invoices into accessible working capital.
The concept is straightforward, but the strategic implications are broader. When receivables represent a significant share of current assets, the way a company finances them can influence its growth rate, supplier relationships, borrowing capacity, and resilience during periods of uncertainty. For owners and financial managers, the relevant question is not simply whether financing is available. It is whether the structure supports the company’s operating model and long-term priorities.
Understanding Accounts Receivable Finance
Accounts receivable finance is a general term for funding that is supported by unpaid customer invoices. Common structures include invoice factoring and asset-based revolving credit facilities. In a factoring arrangement, a company sells eligible receivables to a factor and receives an advance on their value. In a receivables-based line of credit, invoices generally serve as collateral for borrowing under an approved formula.
Although these approaches differ legally and operationally, both seek to shorten the effective cash conversion cycle. Rather than waiting 30, 60, or 90 days for a customer to pay, the business gains earlier access to a portion of the invoice value. The funds can then be used for ordinary business purposes, subject to the terms of the agreement.
This form of financing is most relevant to companies that sell products or services to other businesses or government entities on credit terms. The quality of the receivable matters. Funders typically evaluate whether the invoice represents completed work, whether the customer is creditworthy, whether the obligation is disputed, and whether another party has a prior claim on the receivable.
- Whether the invoice represents completed work
- Whether the customer is creditworthy
- Whether the obligation is disputed or another party has a prior claim on the receivable
Why Profitable Companies Can Still Run Short of Cash
Accrual accounting recognizes revenue before cash is necessarily collected. That distinction explains why reported profit and available cash can move in different directions. A manufacturer may deliver a large order and record the sale this month, but it may have paid for labor and materials weeks earlier and may not collect the invoice until the following quarter.
The same pattern appears in staffing, business services, technology consulting, distribution, and government contracting. Growth increases the amount of money moving through the operating cycle. If customer terms remain unchanged, each new sale may require another investment in labor, inventory, freight, or overhead before cash arrives.
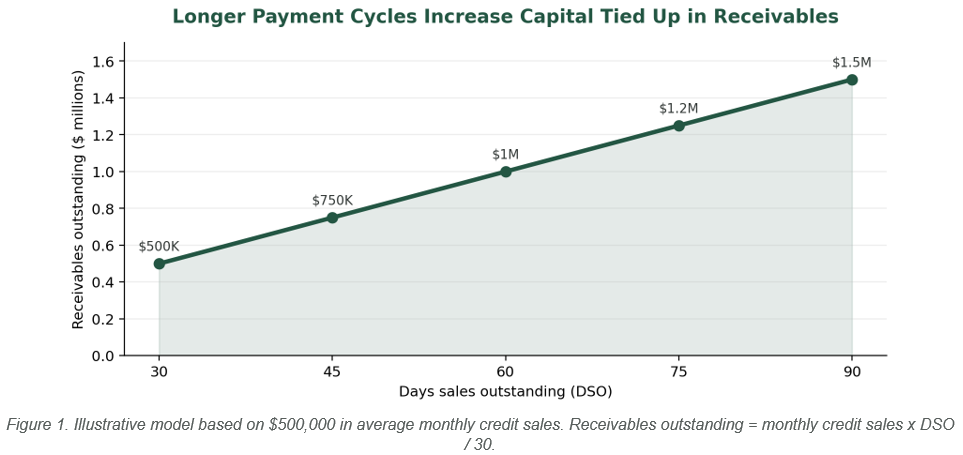
Days sales outstanding, or DSO, is one useful measure of this exposure. As DSO rises, more capital remains locked in receivables. The chart below illustrates the relationship for a hypothetical business with average monthly credit sales of $500,000. It is a simplified model, but it demonstrates why even a modest change in collection timing can materially affect liquidity.
Financing as a Tool for Managing the Cash Conversion Cycle
The chart highlights an operational reality: receivables consume working capital until they are collected. At 30 days outstanding, the illustrative company has approximately $500,000 tied up in invoices. At 60 days, the amount doubles to $1 million. At 90 days, the balance reaches $1.5 million. Sales have not necessarily weakened; cash has simply moved further away from the activity that produced the revenue.
Accounts receivable finance can provide a bridge across this interval. Earlier access to cash may allow a company to:
- Pay employees and suppliers on schedule
- Negotiate purchasing discounts
- Reduce dependence on credit cards
- Pursue new business without waiting for older invoices to clear
In that sense, the value of financing is not limited to emergency liquidity. It can also create operating flexibility.
When the Strategy Is Most Effective
Receivables financing tends to work best when a company has reliable business-to-business sales, creditworthy customers, consistent documentation, and a predictable need for working capital. It can be especially useful during a period of rapid expansion, after winning a major account, while rebuilding liquidity after an unexpected expense, or when seasonal activity creates a temporary funding requirement.
It may also benefit younger companies that have not established the operating history required for conventional bank financing. Because the analysis often places substantial weight on the customer’s ability to pay, a growing business may qualify even if its own balance sheet is still developing.
However, financing cannot correct a weak business model. If invoices are regularly disputed, margins are too narrow to absorb the cost, or customers are unlikely to pay, earlier access to a percentage of receivables will not solve the underlying problem. The company must still maintain sound billing, pricing, and credit practices.
Evaluating Cost in Business Terms
The price of accounts receivable finance varies according to invoice volume, customer quality, concentration, payment speed, advance rate, contract structure, and the level of service provided. A responsible analysis should go beyond the advertised rate. Decision-makers should calculate the expected total cost and compare it with the economic benefit of receiving cash sooner.
For example, financing may be justified if it enables the company to accept profitable orders that would otherwise be declined. It may also create measurable value by:
- Preventing late supplier payments
- Supporting early-payment discounts
- Eliminating more expensive short-term debt
Conversely, financing is harder to justify when the cash will sit idle or support work with insufficient margins.
Contracts should be reviewed for minimum fees, due diligence expenses, transaction charges, concentration limits, reserve requirements, renewal provisions, and termination terms. The company should understand how fees change when customers pay more slowly than expected. Clear modeling under several payment scenarios is more useful than comparing headline percentages alone.
Factoring Versus a Bank Line of Credit
A traditional bank line may be the least expensive option for an established business with strong financial statements, sufficient collateral, stable profitability, and time to complete the underwriting process. It may also offer flexibility for expenses that are not directly connected to specific invoices.
Factoring can be more accessible and may expand with eligible sales. It often includes receivables administration, customer credit review, and collection support. The tradeoff is that factoring may cost more than senior bank debt and typically requires customers to remit payment to a designated account controlled by the factor.
The better choice depends on the company’s stage, urgency, risk profile, and administrative capacity. Some companies use receivables financing as a bridge until they become bankable. Others continue using it because the growth capacity and outsourced receivables support are valuable to their operations.
Operational Considerations Before Moving Forward
Successful financing begins with accurate information. A prospective funder will generally request an accounts receivable aging report, customer list, sample invoices, financial statements, formation documents, and details about existing debt or liens. Depending on the industry, approved time sheets, purchase orders, delivery records, or other evidence of performance may also be necessary.
Management should assess customer concentration because a large balance owed by one customer can affect availability. It should also review billing procedures. Invoices that are incomplete, submitted late, or unsupported by required documents can delay both customer payment and funding.
Communication deserves equal attention. The financing company may interact with customers to verify invoices or discuss payment. A professional process should preserve the business relationship while providing the transparency needed to protect the funder and the client.
Selecting the Right Finance Partner
A finance provider should be evaluated as an operating partner, not merely a source of cash. Industry experience can improve the provider’s understanding of billing practices, customer approval processes, and common disputes. Responsiveness is particularly important when payroll, production, or a major order depends on funding by a specific deadline.
Companies should ask:
- Who will manage the account?
- How availability is calculated
- When funds are released
- How exceptions are handled
References from businesses with similar customers and transaction patterns can provide useful insight. Above all, the provider should be willing to explain the structure in plain language and disclose the full cost before the agreement is signed.
A Strategic Decision, Not Just a Cash Flow Fix
American Receivable has provided invoice factoring solutions to businesses since 1979. As a Dallas-based, owner-managed company, we work directly with clients to understand their receivables, customer base, and working-capital objectives. Our approach emphasizes practical structures, responsive service, and clear communication.
Accounts receivable finance is most valuable when it supports a defined business purpose. It can help close the gap between revenue and cash, but its greater contribution may be the choices it makes possible: accepting the next order, adding the next employee, negotiating confidently with suppliers, or growing without allowing payment terms to dictate the pace of the company. For businesses with sound receivables and a clear plan for the funds, financing can become a disciplined component of growth strategy rather than a temporary reaction to a cash shortage.